6 min
Graded cards in your shop: buying, reselling and VAT
Check before buying, describe in the police register, apply margin VAT and track inventory: the journey of a slabbed card.
Tax and compliance for card shops: margin VAT (art. 297 A), secure POS software, police register and e-invoicing. What the law requires, and by which date.
Margin VAT, the police register, e-invoicing and secure till software (NF525): what the law requires of a second-hand card shop, and by which date. For VAT, start with the margin VAT guide.
Buying from private sellers brings two linked rules into play: the police register, which records each item and its seller, and margin VAT at resale. Two guides cover neighbouring cases: graded cards and consignment. Cards pulled from your own boosters are a separate case: they are new goods, and their VAT is not the buyback VAT.
On tills and invoices, the guides explain who must use secure till software, when to issue an invoice rather than a receipt, the e-invoicing calendar and what e-reporting asks for sales to consumers. A last guide covers DAC7, that is, what platforms report to the tax authorities. These articles are for information: your accountant remains the right person to ask about your own case.
Check before buying, describe in the police register, apply margin VAT and track inventory: the journey of a slabbed card.
The 30 sales and €2,000 thresholds, the data reported, selling a collection versus a commercial activity: what DAC7 changes for anyone selling cards online.
Daily totals per VAT rate, no customer names, at a pace set by the VAT regime: what e-reporting asks of a shop selling to private customers.
Consignment grows your stock without tying up cash. It takes a few clear rules.
Till receipt or invoice: what a card shop must hand over at the till, to a business and for a service, and the margin-scheme VAT wording.
Association, club or shop: what changes when you sell cards and run tournaments, from the 2026 threshold to the lottery limit.
Opening a display and selling the cards as singles is allowed. The trap is tax: these cards are new, not second-hand, and their VAT is not the buyback VAT.
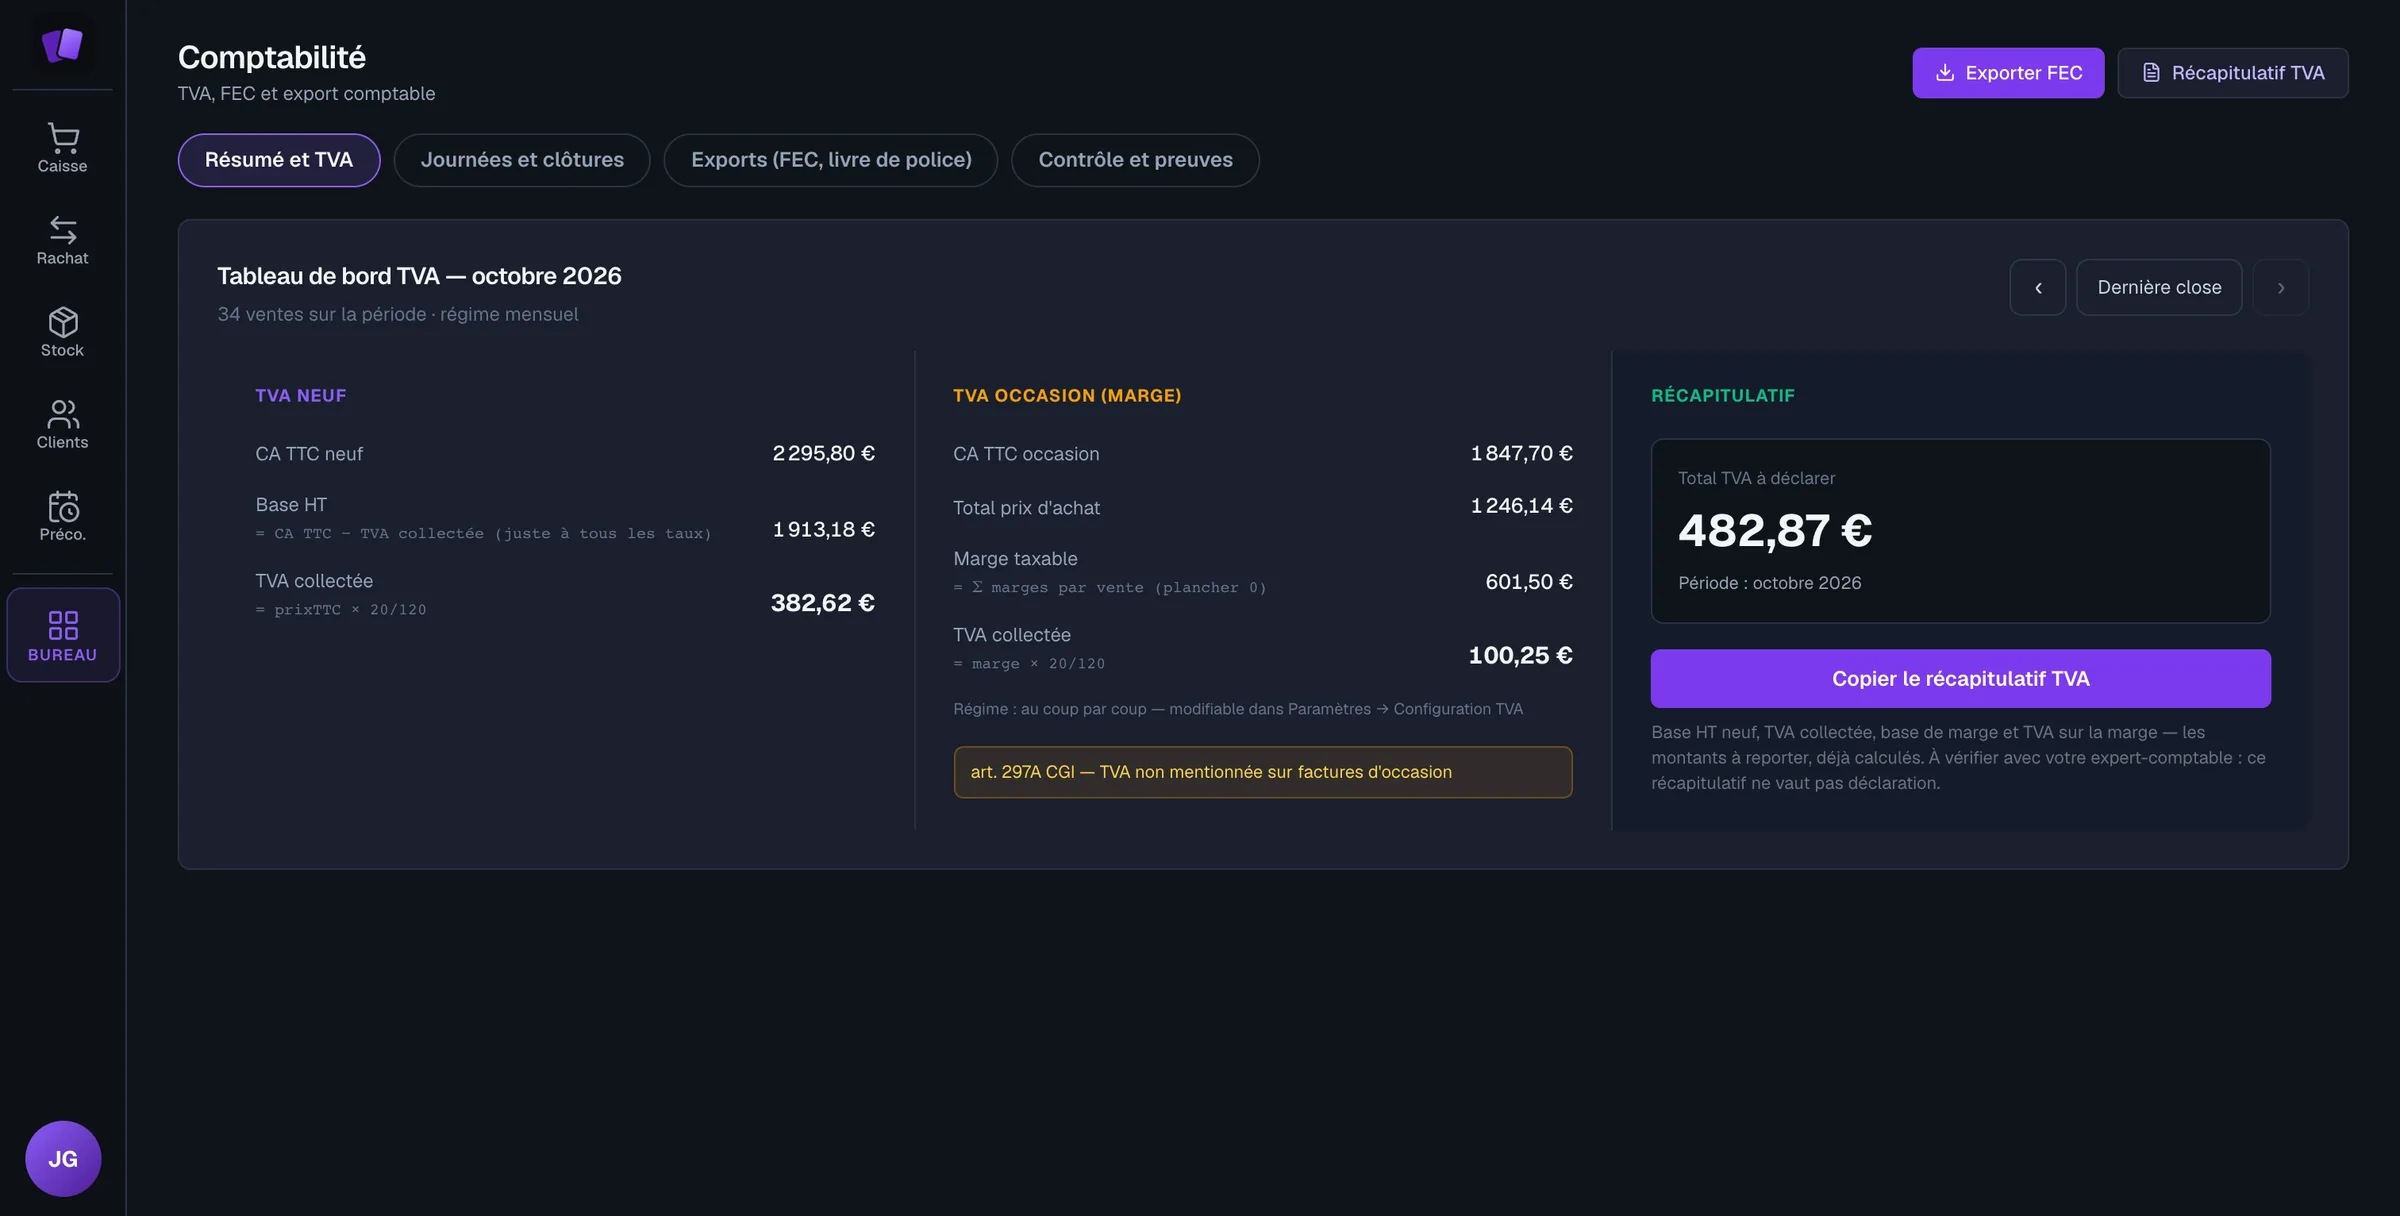
When you buy and resell second-hand cards, VAT is computed on the margin, not the full price. Here's how it works.
Secure POS software in France: who must comply, how to prove it, what the shop risks.
Receiving since September 2026, issuing in 2027: the B2B e-invoicing timeline, and what a TCG shop has to do.
Buying back used cards? Here's why the police register applies to your TCG shop, and exactly what to record at each transaction.